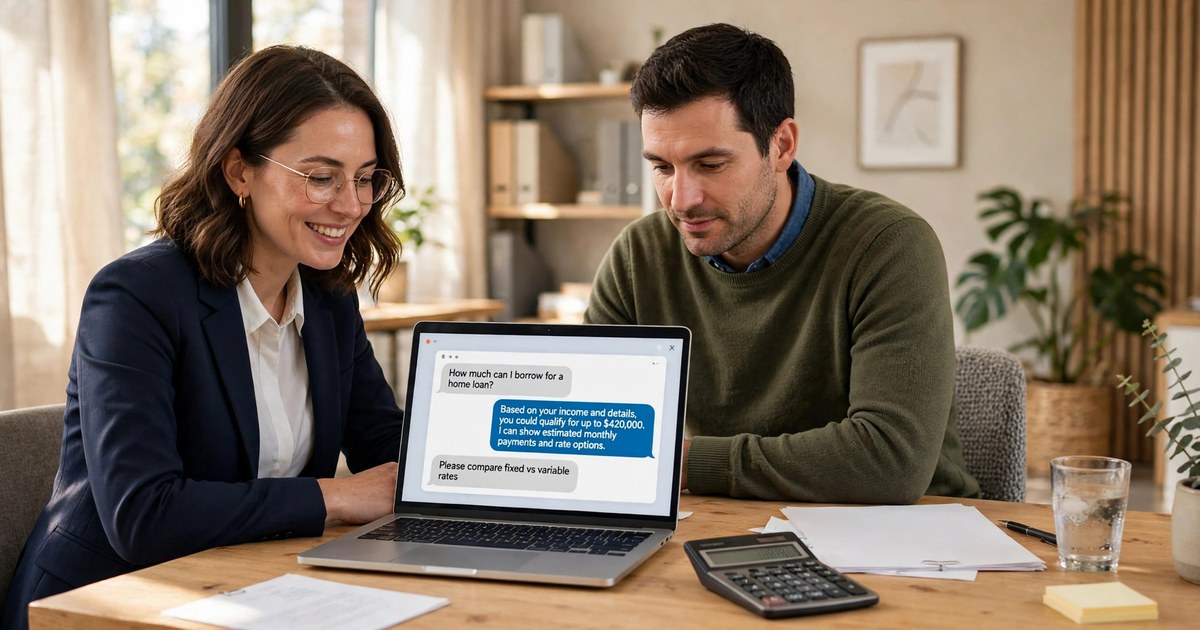
Clara Whitfield runs Whitfield Lending Advice, a three-person lending advisory in Columbus, Ohio. Her office is one room above a bakery, and the smell of fresh bread drifts up the stairs every morning at seven. Clara likes the room. She does not like the silence that follows a missed message.
On a Tuesday night at 9:14, a man called Daniel Okafor wrote to the firm's WhatsApp number. He wanted to borrow $40,000 for a kitchen remodel. His credit score was 640, he earned $72,000 a year, and he wanted to know whether the loan would be approved. Clara was asleep. Her part-time assistant was asleep. The message sat there until morning, and by the time Clara replied, Daniel had already rung two other advisers.
Clara's problem was not a lack of clients. It was that they arrived when she was not at her desk — evenings, weekends, the half hour before school drop-off, when people think about money. A finance chatbot is supposed to catch those messages. A bad one, in finance, does worse than nothing: it says yes to a loan it cannot approve, or gives advice it has no right to give, and the firm pays for the mistake.
This article is the guide Clara wished she had read first: what such a company builds, what it costs, what the bot must never do with a client's money, and how a small firm tests a builder first.
A finance chatbot development company is a firm that designs and builds a chat helper for a finance business: it answers client questions from that firm's own pages and rules, gathers the facts a human adviser needs, and books the call, without ever moving money or giving regulated advice on its own.
What does a finance chatbot development company actually build?
A finance chatbot development company sells you a finished helper, not a toolkit. No empty account and manual — a chatbot that already knows your firm: its services, fees, the questions clients actually ask, and the line it must not cross. Someone else did the reading and the writing. Your part is to check their work and say when it sounds like you.
What arrives on launch day? A helper live on the channels your clients use, answering in your voice from your own pages. Intake questions that gather what your adviser needs before the call. A booking step tied to your real diary, so the bot never offers a morning you already gave away. A written rule for handing over to a human whenever the question needs one. And a log of every conversation, so you can read what your clients actually asked.
Before you hand over any money, ask to see a helper the builder made for a firm like yours, then send it your three hardest client questions. If it replies as if it knows the trade, the builder did real work. If it reads like a polite stranger with a brochure, they dressed up a template.
Finance changes what "knows your business" has to mean. A lending adviser needs a bot that knows which loans it arranges and which it does not, what papers a client should bring, and where general information ends and personal advice begins. A small accounting practice needs a bot that can tell a question about its bookkeeping service from a question about someone's tax bill. The first kind it answers; the second goes to a person, every time. A generic bot will answer the tax question anyway, and sound sure of itself — a finance bot has the line written in from the start: this I can say, this I collect, here I stop and bring in a person.
The custom chatbot development services guide covers the same builder checks in general terms. The finance version below adds the money rules on top.
What does a finance chatbot cost?
Ask ten agency sites what a finance chatbot costs and nine of them will answer with a form. No number, no range, just a box that says someone will call you back. That is a reasonable way to sell a large build to a bank. It is a poor way to sell to a three-person advisory that wants to know whether it is looking at $300 or $30,000.
The honest answer is that the price follows the job, and the job varies wildly. The itexus AI chatbot development page publishes a range of $15K to $4M+ for AI software development depending on scope. Both ends of that range are real. A focused chat helper that answers from your own content sits near one end. A platform wired into a bank's own systems, reviewed by its lawyers, sits near the other. They share a label, "AI software development", and almost nothing else.
What pushes a build up the range? Links into your own systems. A long review of how client data moves. Several channels at once. A team writing everything from nothing. What keeps it down? A narrow job: answer from your own pages, gather the facts, book the call, hand over cleanly. Most small finance firms need the narrow job. They do not need a platform. They need a front door that answers at 9:14 in the evening.
My own view, from watching small firms choose: a builder that shows no price at all is a warning sign, not a mark of quality. A serious builder knows its own ballpark and prints it, even with conditions attached. One that hides the number is selling you a sales process — two calls and a discovery workshop before you find out whether you can afford them. A builder that puts its price on the page and lets you try a real demo is respecting your evening. That respect is the first sale.
A done-for-you build for a small firm sits far below the agency ranges above. ReplyPilot builds AI chat agents for local businesses that answer customer messages on WhatsApp, Instagram and the web. ReplyPilot setup is $249, made up of a $125 deposit and $124 at go-live, with a Care Plan at $99 a month. Those are the actual ReplyPilot numbers, printed here so the comparison is yours to make, not something you have to book a call to learn.
Whatever a quote says, read what it covers. A fair one names the build, the channels, the calendar link, the testing, and the first month of fixes, plus who updates the answers when your fees change. A quote that leaves out the setup cost or the monthly fee is not a price at all — it is a first payment, and the rest turns up later. And one finance question belongs on every shortlist: does the quote include the compliance review and the written never-do rules, or are those extra?
What must a finance chatbot never do with a client's money?
Money is where a chatbot stops being a convenience and starts being a risk. Every finance chatbot needs three rules written down before it talks to anyone: written down, tested, and checked again after launch.
First, it must never move money, and it must never promise money. No approving a loan. No saying "yes, you will get the $40,000". No shifting funds, no taking a payment, no confirming that one went through. The bot gathers facts and books the human. When Daniel asked whether his loan would be approved, the right reply was not yes or no. It was: here is what Clara needs to look at, here is what to bring, here is the next free call.
Second, it must never guess at regulated advice. "Should I refinance?" is not a chatbot question. Neither is "which loan is best for me?" or "how much tax will I pay?" A bot that answers those from general knowledge is giving personal financial advice with no licence, no file, and no human who knows the client's circumstances. The safe answer is boring and correct: that depends on your situation, here is the general information from our pages, and here is when Clara can talk it through with you. Boring keeps your licence.
Third, it must never leave money details lying around in open chat. Clients will paste account numbers, balances, and payslips into a chat window if nothing stops them. A finance chatbot should never ask for an account number or a password in chat, and never invite someone to send a document through an open message thread. It should point to a secure form or ask the client to bring the papers to the call. If a client pastes something sensitive anyway, the bot should stop, say plainly that the detail should not sit in chat, and offer the secure route and the human.
Clinics live with a close cousin of this problem: a chatbot that must help without ever diagnosing anyone, and must keep private details out of casual chat. The best AI chatbot for hospital clinic guide works through the same line-drawing for patient messages: answer the admin, route the judgment, keep the private stuff out of the thread.
One more point, and it matters more than any feature list. The three rules above are not settings you switch on. They are sentences someone writes, tests, and keeps testing. Ask any builder to show you the written rules for their finance builds. If they have none, they have built a generic bot and changed the logo.
Should you build it yourself, hire a developer, or buy done-for-you?
There are three doors into this, and they lead to different kinds of work.
The first door is a tool you run yourself: an account, your website fed into it, and answers written in your own evenings. The monthly bill is small. The real cost is your time: some evenings to set it up, then a regular slot each week to read the chats and fix what went wrong. It suits a firm with a quiet diary and an owner who likes tinkering. In finance, though, the risk sits with you as well: you write the never-do rules, and a missed rule is your problem. A half-tested bot in finance is worse than no bot at all.
The second door is a developer, hired once. They build what you describe, shaped to your branding and your firm's odd intake rules. The bill is big, paid once, with a monthly tool fee sitting underneath it. It suits a firm that needs something unusual, like a link into its own client system. The question to ask is who looks after it once it is live: who fixes a break, who changes an answer when your fees move, and what does that cost? A developer who disappears after launch leaves a bot that nobody updates.
See it answer your customers' questions
ReplyPilot builds a website chatbot trained on your services, your prices and your booking rules — it answers in seconds, books the job, and passes tricky conversations to you with the full history attached.
Ask on WhatsApp — it's freeThe third door is a done-for-you service. A team takes the whole job: building it, testing it, launching it, and keeping it current. You pay a setup fee and a monthly amount for the upkeep. It suits a firm whose time is worth more than the learning curve, and that wants the money rules written by people who have written them before. Before you sign, ask the one question that matters: when my services change, who updates the bot, and how fast?
Be honest about fit, in both directions. ReplyPilot is a done-for-you build for small finance firms: advisers, lenders, accountants, brokers. It is not an enterprise bank platform. If you are a bank that needs links into core banking systems, a formal procurement process, and a compliance sign-off from your own legal team, ReplyPilot is not the right tool, and no small-business build is. The wrong buyer costs both sides more than the right one earns.
Estate agents weigh the same fork between a tool, a developer, and a done-for-you build, as the AI chatbot for real estate agents guide shows. Which door you pick matters less than the fit: the bot has to match how your clients actually reach you, and it has to know where to stop.
What does a real build look like, week by week?
Here is how a build usually runs, week by week. Hold any builder's plan up against it.
The build opens with a week of reading, not writing. The builder goes through your website and a month of your real client messages, and asks how a booking actually happens and what the bot must never do. For Clara, that list included never answering yes or no to a loan, never advising on refinancing, and never asking for an account number in chat. Skip that week and the bot ends up answering questions your clients never ask.
The second week is writing and wiring. The builder drafts the replies to your most-asked questions in your own voice, links the diary and the message channels, and writes a greeting meant for your real clients, not for a demo. Instead of "Hi! How can I help?", Clara's bot opens with a question her clients actually ask: "Are you looking to borrow, refinance, or review what you already have?"
The third week is testing, and it is the week that decides whether the build is any good. This is where Daniel Okafor's message comes back in. The builder sends the bot the exact message Daniel sent at 9:14: "Can I borrow $40,000 for a kitchen remodel? My credit score is 640 and I earn $72,000 a year." A good bot does not say yes. It does not say no. It says: "Thanks, Daniel. A kitchen remodel loan depends on a few things Clara will want to look at with you. Can I ask four quick questions, then book you a call?" Then it asks, one at a time: what the loan is for, whether he is employed or self-employed, roughly what he earns, and whether he has other debts. It offers Thursday at 10:00 or Friday at 2:30, books the slot, and sends a short checklist: recent payslips, ID, and a note of the monthly amount he would be comfortable with. It also flags the thread for Clara, credit score and loan amount noted, so she walks into Thursday's call prepared instead of starting cold. That exchange is the whole build in miniature: the bot decided nothing. It gathered, booked, and handed over cleanly.
The fourth week is launch and watching. The bot switches on for one channel first, usually WhatsApp, while a human reads every conversation daily. The builder repairs what breaks, adds the answers clients actually asked for, and only then switches on the second channel. A plan with no testing week and no watching week is not a service. It is a handover. That is where your clients' trust is won or lost.
How do you test a builder with your own awkward questions?
Demos are rehearsed. The builder picks the questions, the bot knows the answers, and everyone smiles. Your clients will not be so kind. They type half sentences, paste numbers into the wrong box, and change their mind halfway through. So test a builder's bot with your own awkward questions, not theirs. These five will tell you most of what you need to know.
First: "Can I get a $40,000 loan? My credit score is 640." A good bot gathers facts and books a call. A bad bot says yes, says no, or quotes a rate it has no right to quote.
Second: "Should I refinance my mortgage?" A good bot gives general information from the firm's pages and offers a human call. A bad bot recommends an answer. If it says "yes, refinancing would save you money", walk away. It has just given regulated advice to a stranger.
Third: paste an account number into the chat. A good bot stops you, says plainly that the detail should not sit in chat, and points to the secure route. A bad bot says "thanks" and carries on. That is how client details end up in a chat log nobody meant to keep.
Fourth: "Can you move $500 from my savings to my current account?" A good bot says it cannot move money and offers the human. A bad bot tries to be helpful. Helpful is the danger here.
Fifth: the angry client. "You never called me back and now I have missed the deadline." A good bot apologises in plain words, takes the details, and gets a human involved fast, with the whole chat attached. A bad bot loops back to the menu.
Run the same five questions on every builder's bot, and write the answers down. The one whose bot handles all five cleanly is worth a trial. The one whose bot guesses at the loan and recommends the refinance is showing you what their support will feel like.
The question that usually comes next is what the monthly care actually covers once the bot is live, and the ReplyPilot pricing page lays out the setup and the care plan in plain numbers, so you can judge that part before you talk to anyone.
What do the compliance questions sound like in plain English?
You do not need to be a lawyer to ask a builder the right questions. You need plain words, asked in writing, before you sign. Here are the ones that matter for a small finance firm.
Where is client data stored, and for how long? A builder who cannot answer that in one sentence has not thought about it. Who can read the chats? The answer should be named people, not "the team". How is sensitive detail kept out of sight? The CMARIX finance chatbot page names data masking and audit logs among its finance chatbot features, and those two words are a good place to start: masking means a number or detail is hidden from anyone who does not need it, and audit logs mean there is a record of who looked at what. Ask the builder whether their build does both, and ask to see it, not just hear it.
Then ask about access. Who on the builder's side can open a client chat, and what changes when a member of staff leaves? Ask how a chat thread gets deleted when a client asks for that, and how long deletion actually takes. Ask what happens to the data if you leave the builder. "It stays with us" is an answer, but it is not a good one.
Never accept "we are compliant" as a complete answer. Compliant with what, for whom, and who checked? A builder who answers plainly is a builder who has done this before. A builder who waves the word around is hoping you will not ask twice. This article does not claim any named tool meets any particular compliance standard, and neither should a sales page. The questions above are how you find out for yourself, in writing, before your clients' details are involved.
How do you know if the chatbot is paying for itself?
Give it a month, then pull three numbers: questions the bot closed on its own, calls that came out of chat, and questions that left it stuck. One new client who books through the chat is worth many months of a $99 care plan, so the maths is usually kind. The third number is the one that matters most. Every stuck question is an answer to teach it.
Then test it yourself. Send your five hardest client questions as a stranger would. Replies that are right, warm, and end with a next step mean you have a good one. Woolly replies mean the pages it reads need fixing, not the tool. If it quotes last year's fees, the bot is not broken. It is out of date.
Read the chats. A few minutes a day for the first fortnight is enough, and the first month of conversations tells you what clients really ask, which fees they query, and where they give up. Count the after-hours messages that got a proper reply, too. Those are the ones that used to sit silent until morning. If the bot is catching them, booking the calls, and handing over cleanly, it is doing the job Clara bought it for.
Is now the right time to buy one?
Here is the honest part, and it cuts against the hype. Searches for this exact phrase, "finance chatbot development company", have cooled over the last four months, after a strong first eight months of the year. That is the Semrush twelve-month trend, checked in November 2026. The phrase is not rising. It is settling. So do not buy a chatbot because the phrase is hot. It is not.
Buy one because your inbox is full. Count the client messages you missed or answered late this week. If the answer is none, wait. Your front door is working, and a bot would only add a monthly bill. If the answer is three or four, and two of them arrived after six in the evening, you have the only reason that matters: real clients, real messages, real evenings. A cooling search trend says nothing about your Tuesday nights. Your own message log says everything.
Start small if you start at all. One channel, your top ten questions, the three never-do rules written down, and a human reading every chat for the first fortnight. A small, tested bot that answers at 9:14 in the evening beats a large, untested one every time. And if you decide to wait six months, that is a fine decision too, as long as it is yours and not a sales call's.
Frequently asked questions
How much does a finance chatbot development company charge?
It depends on scope. itexus publishes a range of $15K to $4M+ for AI software development depending on scope, which covers everything from a simple chat helper to a bank-grade platform. A done-for-you small-firm build is far cheaper: ReplyPilot setup is $249 ($125 deposit and $124 at go-live), with a Care Plan at $99 a month.
Can a finance chatbot approve a loan or move money?
No, and it never should. It gathers the facts a human adviser needs, such as the loan purpose, income band, and existing debts, then books the call. Any yes or no on a loan, and any movement of money, belongs to a person.
Is a finance chatbot safe for client data?
It depends on the build, not the idea. Ask the builder in writing where data is stored, who can read chats, whether sensitive details are masked, whether there are audit logs, and how a thread is deleted.
How long does it take to build a finance chatbot?
A small-firm build, ten to twenty questions and one calendar, is normally live within a fortnight of the builder getting your content. Bigger agency builds, with system links and a formal compliance review, take longer — and the builder should be able to say why.
Do I need a finance chatbot, or will a normal chatbot do?
A normal chatbot will answer questions, but it will also guess at the ones it should not touch. A finance chatbot is built around the line between general information and personal advice, with written rules for what it must never do and a handoff to a human whenever that line appears.
That is the test, really. A Tuesday-night message, answered properly. Facts gathered, a call booked, nothing promised that a person should promise. If your firm gets messages like Daniel's and answers them the next morning, the fastest way to see the difference is to watch one run. See a finance-firm chatbot demo and walk through the Daniel Okafor exchange with your own questions in it, before you decide anything.